Published October 2, 2026
The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get
The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get
If you’ve been watching mortgage rates and thinking, “Maybe I should wait to buy,” you’re not alone.
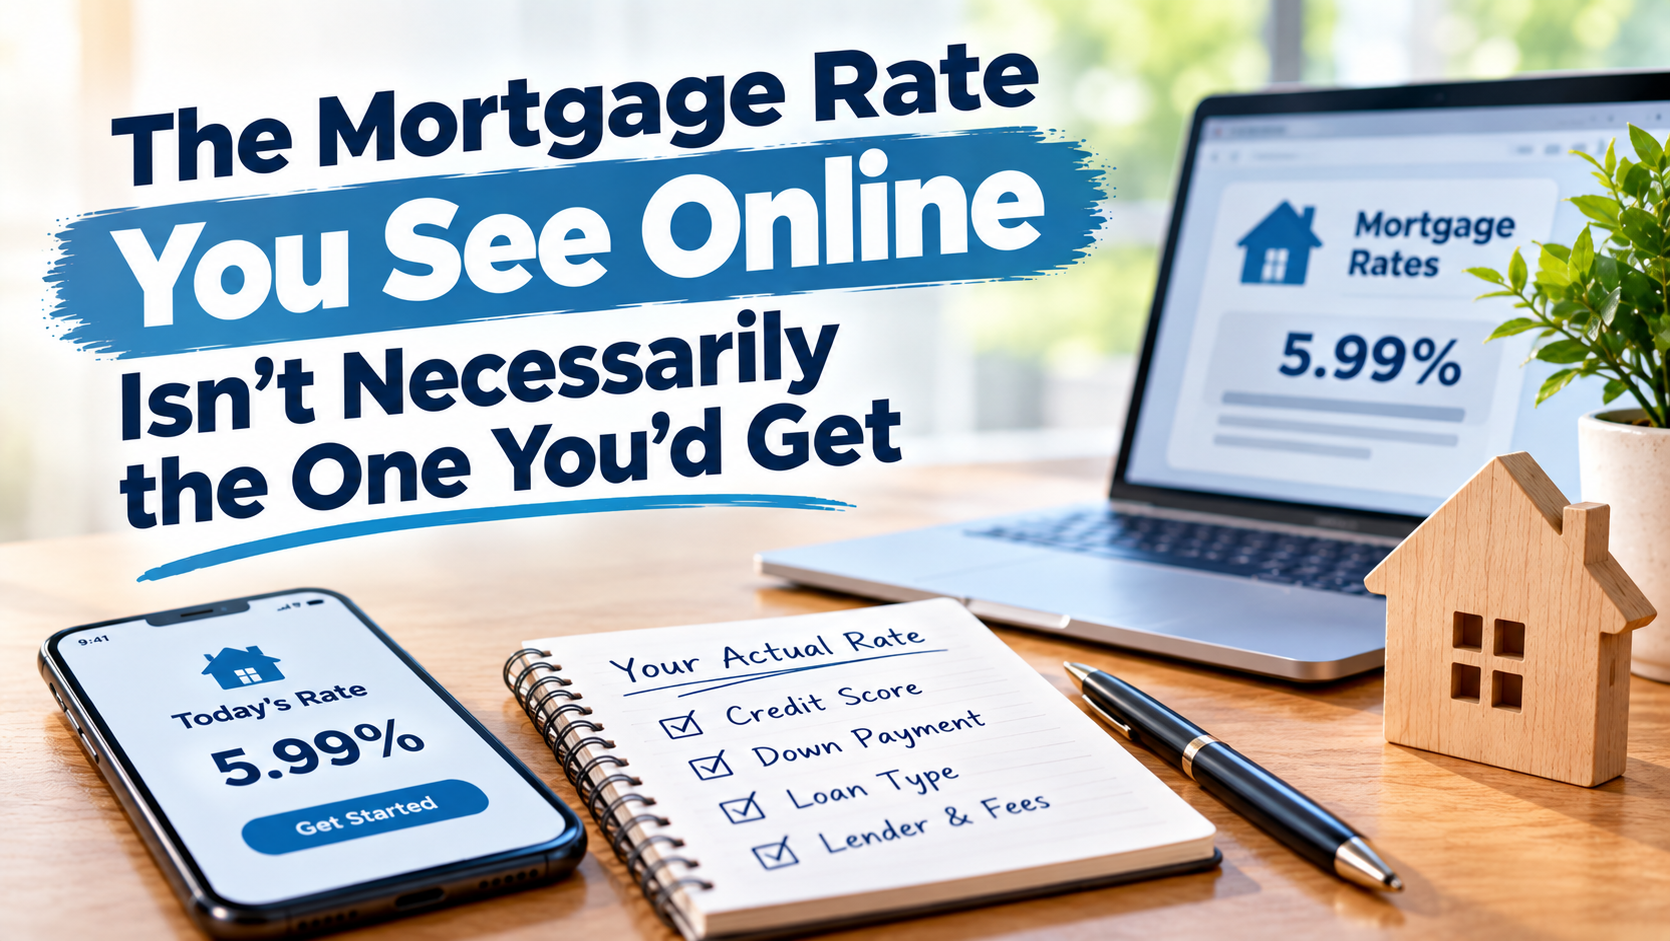
But there’s one important thing we want New Jersey homebuyers to remember: the mortgage rate you see online or in a headline isn’t necessarily the rate you would actually get.
Mortgage rates can change frequently, and your individual rate depends on much more than the number you see advertised.
What Determines Your Mortgage Rate?
When you’re buying a home in New Jersey, your lender will look at your personal financial picture, including:
- Credit score: A stronger credit profile may help you qualify for more favorable loan terms.
- Debt-to-income ratio: Your monthly debts compared with your income can affect your loan options.
- Down payment and loan-to-value: The amount you put down can influence your financing.
- Loan program: Conventional, FHA, VA, and other mortgage programs can have different requirements and rates.
- Overall financial profile: Your income, assets, debts, and other factors all matter.
That means two buyers looking at the same $600,000 home in Bridgewater, Edison, Hillsborough, or Princeton could potentially receive different mortgage terms.
Don’t Overlook Seller Concessions
In some New Jersey transactions, there may also be opportunities to negotiate seller-paid closing costs or other concessions, depending on the property, contract, and loan guidelines.
For example, if you’re purchasing a home in Central New Jersey, negotiating certain closing costs could help preserve cash for your down payment or other upfront expenses.
There are also situations where a mortgage rate buydown may make sense. Your lender can explain whether that option fits your financial situation.
Your First Step Should Be a Pre-Approval
If you’re serious about buying a home in New Jersey, we recommend starting with a conversation with a qualified lender.
A pre-qualification generally provides an early estimate based on information you provide.
A pre-approval typically involves verification of your financial information and can give you a clearer picture of your purchasing power.
That can make a big difference when you're searching for homes in competitive markets such as Middlesex, Somerset, Morris, or Hunterdon County.
Instead of asking, “What mortgage rate is everyone talking about?” ask:
“What mortgage rate and monthly payment could I qualify for?”
Those are the numbers that matter to your home-buying decision.
What Should New Jersey Buyers Ask Their Lender?
Before you start seriously shopping, consider asking:
- What monthly payment fits comfortably within my budget?
- How would a change in mortgage rates affect my payment?
- Should I consider a different loan program?
- Would a larger down payment make sense for me?
- Are there opportunities for seller concessions or a rate buydown?
- What would it cost me to wait 3, 6, or 12 months?
Once you understand your actual options, you can make a decision based on your financial situation—not a mortgage-rate headline.
Bottom Line
The mortgage rate you see online is a starting point, not necessarily your personal rate.
If you’re thinking about buying a home in New Jersey or Central NJ, getting pre-approved can help you understand your real purchasing power before you begin your search.
At The Bansal Team, we help buyers understand the local market, evaluate their options, and navigate the home-buying process with confidence.
The right question isn't “What rate is in the news?”
It’s “What does my rate look like?”