
Published February 2, 2026
Is 6% the New 3%? 2026 New Jersey Mortgage Rate Guide

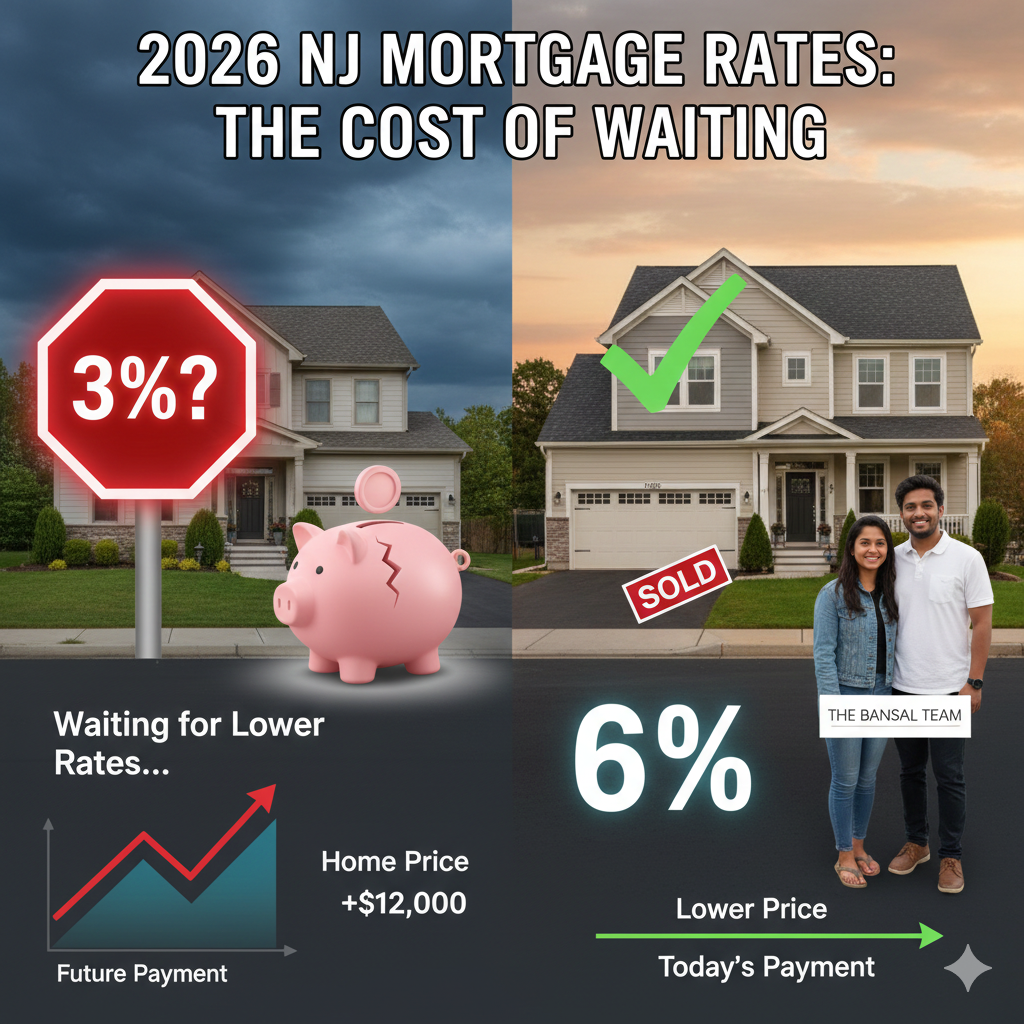
Is 6% the New 3%? Why Waiting for Lower Rates Could Cost You More in 2026
As we move through January 2026, the question we hear most often at The Bansal Team isn't "Should I buy?" but rather, "Should I wait for rates to hit 4% or 5% again?"
It’s a fair question. After the historic (and frankly, anomalous) 3% rates of the early 2020s, today’s average 30-year fixed rate of ~6.03% can feel like a hurdle. However, the data across New Jersey suggests that waiting for a significant drop in rates might be the most expensive decision a buyer can make this year.
Here is a deep dive into why 6% is the new "sweet spot" and why "timing the rate" often leads to "missing the house."
1. The Appreciation Trap
While you wait for mortgage rates to drop by 1%, New Jersey home prices aren't standing still. Industry forecasts for 2026 predict a nominal home price appreciation of approximately 2% to 2.5% across the Garden State.
In a market like New Jersey, where the median home price is hovering near $550,000 - $600,000, a 2% increase means the house you want today will cost you $12,000 more by next year.
The Math: If you save $200 a month on a lower interest rate but pay $15,000 more for the home, it takes you over 6 years just to break even on that "savings."
2. The "Floodgate" Effect
There is a massive amount of "pent-up demand" in New Jersey. Many buyers are sitting on the sidelines, waiting for rates to dip below 6%.
The moment rates hit 5.5%, those buyers will all rush back into the market at once. In a state with notoriously low inventory like NJ, this spike in demand inevitably leads to:
- Bidding Wars: Homes selling for $30k–$50k over asking.
- Waived Contingencies: Buyers losing their leverage on inspections and appraisals.
- Higher Entry Prices: The competition drives the price up faster than the rate savings can keep up.
By buying at 6%, you are competing against fewer people. You have more room to negotiate, more time to think, and a better chance of keeping your inspection protections intact.
3. The "Date the Rate, Marry the Home" Reality
One of the most important shifts in 2026 is the stabilization of the "Lock-In Effect." For the first time, the share of homeowners with rates above 6% has surpassed those with rates below 3%. The market is finally moving again.
If you buy today at 6% and rates eventually do drop to 5%, you can refinance. You can change your rate, but you can never change the price you paid for the home. If you wait and the price goes up, that cost is locked in forever.
4. 6% is Historically "Normal"
Context is everything. While 3% felt great, the 50-year historical average for mortgage rates is actually closer to 7.5%. In the grand scheme of New Jersey real estate history, a 6% rate is an excellent entry point—especially when paired with the steady equity growth our state is known for.
Strategy for 2026: Focus on "Monthly Comfort," Not "Rate Perfection"
At The Bansal Team, we encourage our clients to focus on the monthly payment they can comfortably afford today. If the numbers work at 6%, buy the home. If rates go down later, it’s a bonus. If prices go up (as they almost certainly will in NJ), you’ll be glad you’re already on the winning side of the equity curve.
Ready to see what your monthly payment would look like in today’s NJ market?
