Published September 30, 2026
3 Things You Can Actually Control About Your Mortgage Rate Right Now
3 Things You Can Actually Control About Your Mortgage Rate Right Now
If you’re thinking about buying a home in New Jersey, affordability is probably one of the biggest things on your mind. And when mortgage rates move higher, it’s natural to wonder whether you should wait for rates to come back down.
The reality is, you can’t control where mortgage rates go next. Rates are influenced by inflation, economic data, global events, oil prices, and Federal Reserve decisions.
But here’s the good news: there are several things you can control that may affect the mortgage rate and payment you qualify for.
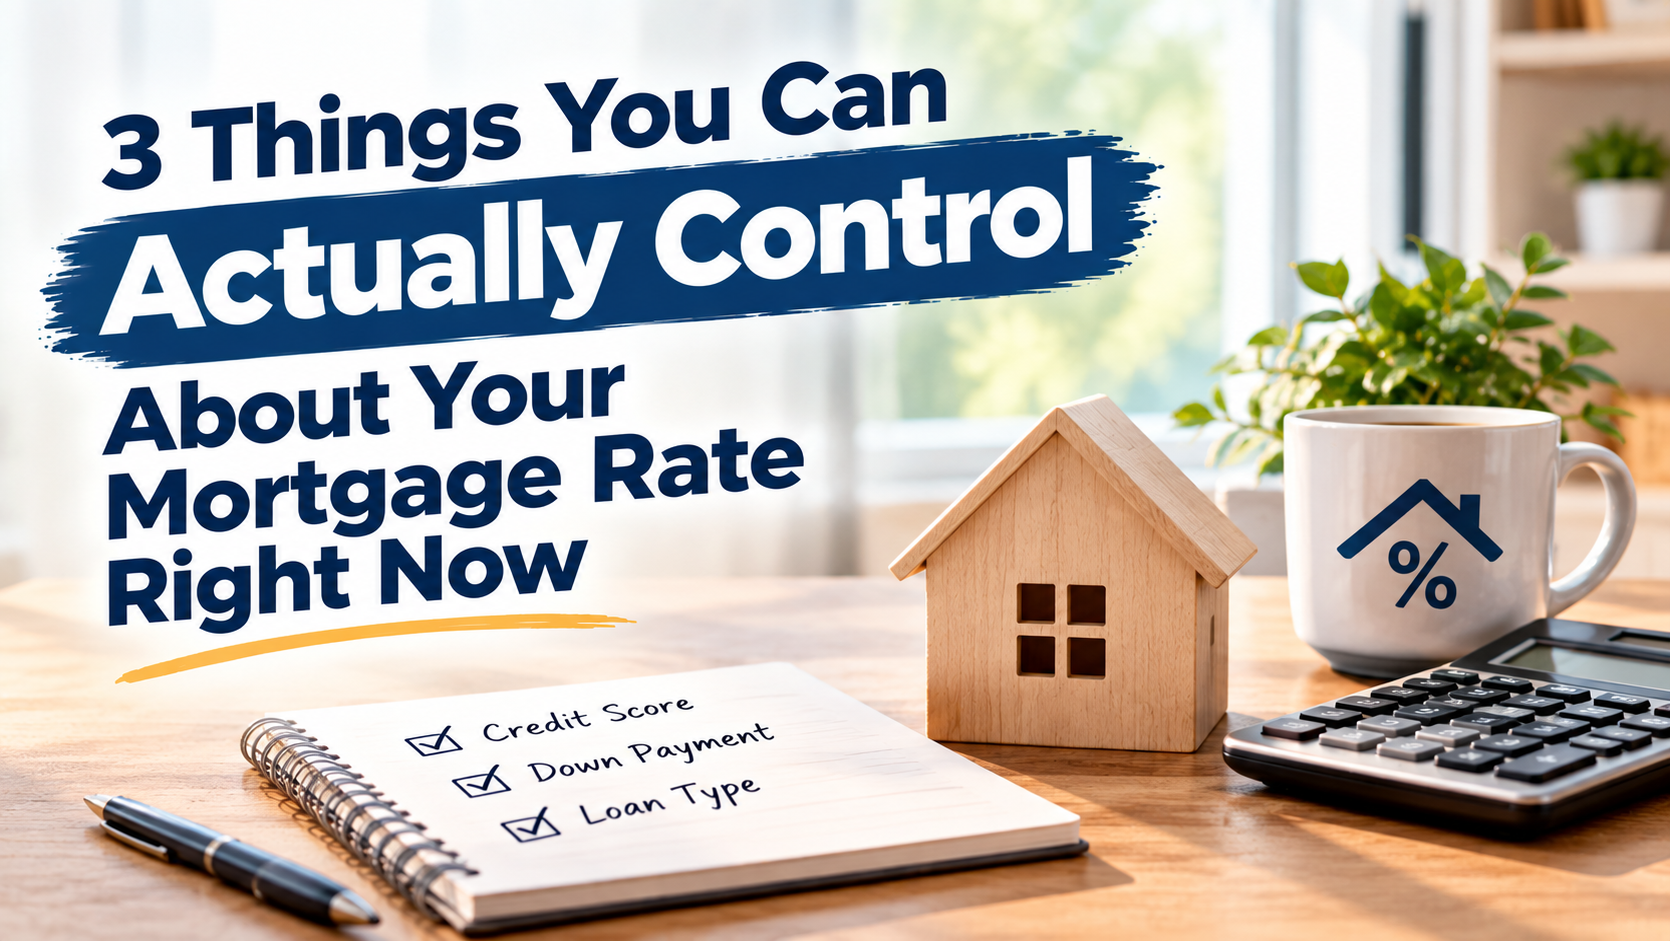
1. Take Care of Your Credit
Your credit score can play an important role in the mortgage rate and loan terms available to you.
Before buying a home in New Jersey, review your credit, pay bills on time, avoid taking on unnecessary new debt, and talk with a trusted lender about ways to strengthen your application.
For example, if you’re planning to buy a home in Bridgewater, Edison, Piscataway, Hillsborough, or another Central New Jersey community, improving your financial profile before you start shopping could make a meaningful difference in your overall borrowing costs.
2. Explore Your Mortgage Options
Not every buyer needs the same type of mortgage. Conventional, FHA, VA, and USDA loans have different requirements, while choosing a 15-, 20-, or 30-year term can change both your monthly payment and the total interest you pay.
A fixed-rate mortgage provides predictable payments, while an adjustable-rate mortgage may offer a different initial rate but can change later.
That’s why we recommend comparing your options with a qualified lender before deciding what works best for your situation. It can also be helpful to compare offers from more than one lender and look beyond the interest rate alone—including closing costs, fees, and loan terms.
3. Consider New Construction
Another option worth exploring is a new construction home.
Some New Jersey builders offer incentives such as mortgage-rate buydowns, closing-cost assistance, or other financing incentives to attract buyers. These incentives can potentially reduce your monthly payment, depending on the specific program and your loan.
If you’re considering a new construction community in Central New Jersey, Somerset County, Middlesex County, or surrounding areas, ask your real estate agent and lender whether any current builder incentives are available.
The Bottom Line
You may not be able to control mortgage rates—but you can control how prepared you are to get the best terms available to you.
Your credit profile, mortgage choice, and type of home can all play a role in your overall affordability.
At The Bansal Team, we help New Jersey buyers understand the local market, evaluate their options, and make informed decisions based on their goals and budget.
If you’re thinking about buying a home in New Jersey, let’s talk about what your next step could look like.